How to Present a Pitch Deck and Protect Your Idea
How to present a pitch deck: a first-meeting run of show, an answer sheet for investor questions, what to disclose at each stage and the follow-up.

Investors spend under 3 minutes reviewing a deck, so the talk adds reasoning, answers and a dated next step.
The forwarded file is read alone; the meeting version leaves room for the speaker.
Market, traction, team, proceeds, valuation and risk each get a prepared answer with a source.
The claim goes in the teaser, the result in the presentation and the method in the data room.
The PDF and the promised answers go out the same day, with the next step dated.
How to present a pitch deck: start from the fact that the investor has often read it alone before the meeting begins. The talk adds the reasoning behind each claim, the answers to what the pages leave open and a dated next step.
Preparation covers four things: the talk, the questions, the follow-up and what you disclose.
How to present a pitch deck to investors in a first meeting
A first meeting starts with the investor already holding a view. Research from DocSend, whose platform hosts the decks it measures, puts the time investors spend reviewing a pitch deck at less than 3 minutes.
In its 2020 pre-seed data, decks that raised were read for over four minutes and decks that didn't for one minute 30 seconds. The first minute of the talk confirms the investor's view or corrects it.
Before the meeting, settle three things with the investor's office: who attends, how long the slot is and whether they have the teaser. A partner who joins without having read it changes which version you present.
The run of a first meeting follows the slide order in the pitch deck outline, with the talk doing different work at each beat:
The first minute states the claim the whole deck makes and what you want from the meeting.
The middle moves through the evidence, and the talk gives the reason behind each number before the investor asks for it.
Interruptions get answered in the order asked; the talk then returns to its slide.
The last two minutes make one ask: a second meeting, a named colleague or access to a data room.
One teaser to send ahead, one version to present
A deck that gets forwarded and a deck that gets presented do different jobs, so they run as two files. The teaser is read alone, often by someone the company has never met, and makes its argument in full sentences on the page. The presentation version leaves room for the speaker: fewer words per slide, one claim each, the reasoning in the talk.
The test for the teaser is whether a partner who forwards it has to add any explanation of their own.
4 columns. Drag the table sideways; the first column stays put.
Meeting | Format | What leads | What stays out |
|---|---|---|---|
First meeting or intro call | Teaser sent ahead, short presentation version | The one-sentence claim and the evidence behind it | The full model and the method |
Partner or committee meeting | Presentation version, plus a PDF the partner can forward | The reasons the partner will repeat to colleagues | Slides that restate the teaser |
Follow-up after diligence questions | Written answer pack | The pages whose numbers changed, with sources | The story retold from the start |
Both files start from the argument a reader has to repeat, fixed before either is designed, which is also the order of a pitch deck service engagement: strategy, story and research first, design last.
A robotics company gave us its own summary of its earlier investor pitches. Investors had asked how hard it would be to bring the system to a new crop, and the market claims on the slide needed a source. The company had also been turned down earlier for sounding too narrow.
We built two files from that summary, a teaser to send before the meeting and a presentation version to speak from, and the client approved both.
Your own earlier pitches hold the same material. List the questions investors asked, the claims that needed a source and the reasons you were turned down, and write the answer sheet below from that list before you touch a slide.
How to make a good pitch deck for a live presentation
Every slide in a live meeting carries one claim, and every chart has to read without the speaker; the talk adds the story. Harvard Business School Online's guide pairs spreadsheets and charts with a story about where the company is going.
Test every slide against four questions before it goes in:
Can the investor say the slide's claim back at a glance?
Does every number on it carry a source?
Does the chart read without the speaker?
Does the slide need to be in the room, or can it sit in the data room?
Run the four questions slide by slide, fix what fails on sources, and move the rest to the data room before the deck goes to anyone, the forwarded teaser included.
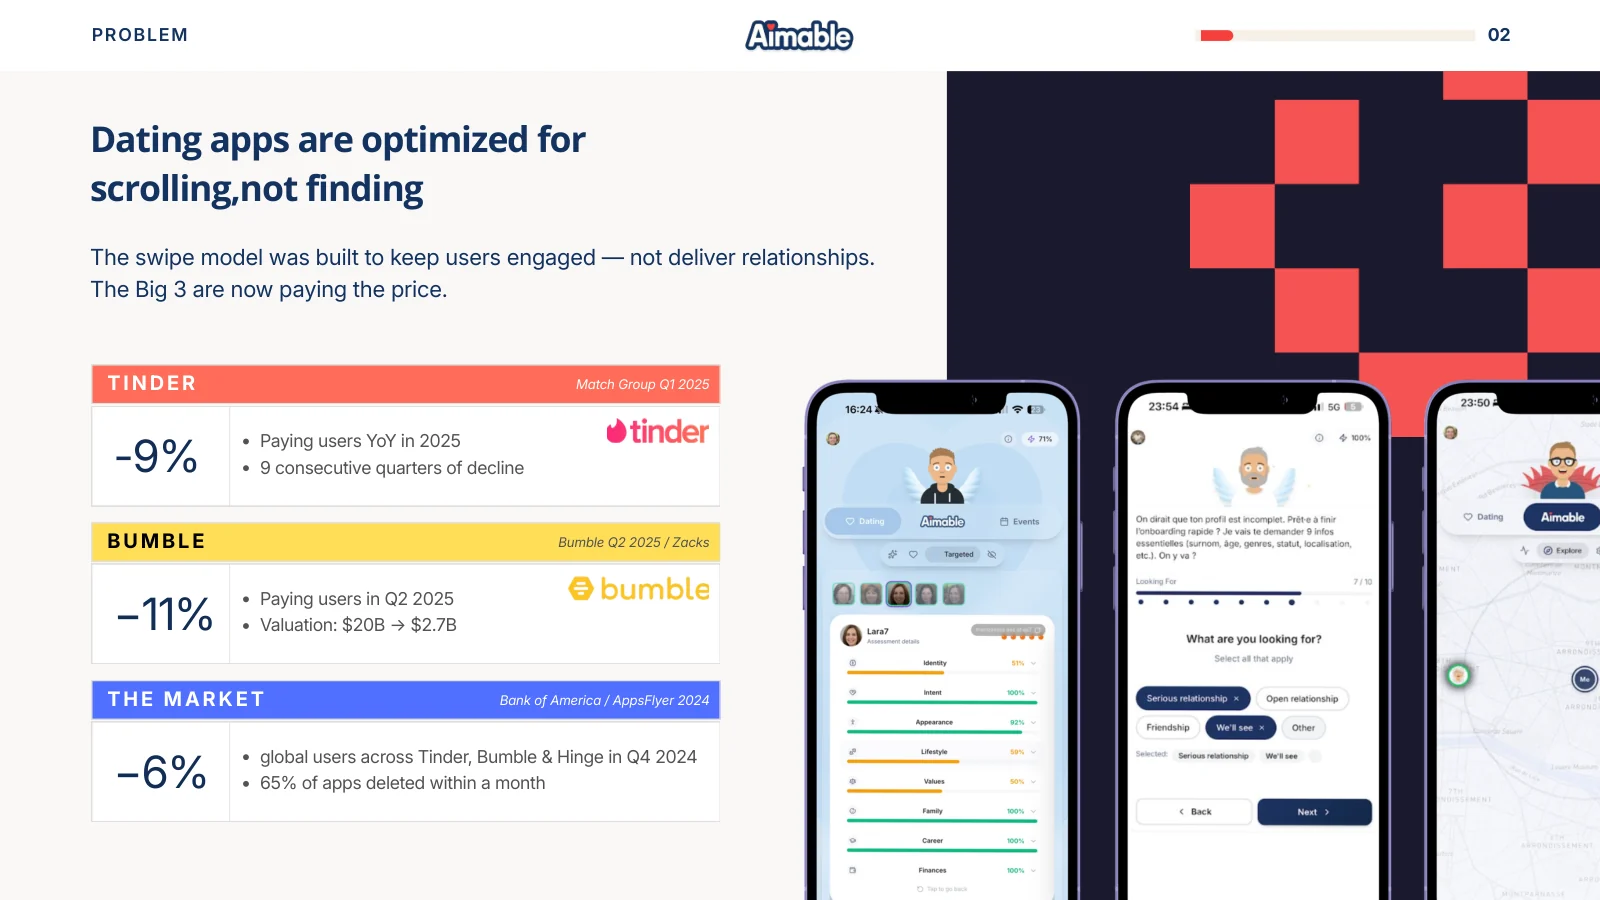
The problem slide above passes the first two questions on sight: one claim in the headline, and a named source and date beside each of its three headline figures.
How to present a pitch deck: pacing the talk around the slides
A talk that follows the slides sentence by sentence repeats what the investor has already read.
A live presentation deck typically runs 12 to 15 slides, so the twelve minutes of deck talk in the chart below leave 48 to 60 seconds a slide before any questions. A slide that needs longer than that to explain moves to the data room.
| Track | What | When |
|---|---|---|
| Opening claim and the ask | 0 to 1 minutes | |
| Deck, slide by slide | 1 to 13 minutes | |
| Investor questions | 2 to 13 minutes | |
| Close: one ask | 13 to 15 minutes |
When an investor interrupts, answer in one or two sentences, tie the answer to the slide on screen and say where the fuller one sits: "the numbers are two slides on". If the question changes the order of the talk, follow it.
How to pitch to investors by type
2 columns. Drag the table sideways; the first column stays put.
Investor | Asks first |
|---|---|
Fund partner | Thesis fit and the return case |
Family office | Who is behind the company and who else is investing |
Strategic or corporate investor | The link to its own business |
Individual investor | What the money will pay for |
Before the meeting, rehearse once against a clock with someone playing that investor type, using the answer sheet below. Cut any slide that draws no question and carries no claim.
How do you handle investor questions after the deck?
An answer sheet written before the meeting, by question type, means each answer starts from a source the company already holds. The sheet needs one row per type:
3 columns. Drag the table sideways; the first column stays put.
Question type | What the investor is testing | What a good answer contains |
|---|---|---|
Market size | Whether the market supports the return | The source of the figure and the part the company can reach |
Traction | What sits behind the headline number | The number, its definition and the period |
Team | Who's missing | The gap named, and the plan to fill it |
Use of proceeds | Whether the plan is specific | The allocation by purpose and what each part buys |
Valuation and structure | How the company thinks about price | The reasoning and the options it weighed |
Risks | Whether the company sees them | The largest two, each named in a sentence, then what the company gains by getting past each, with the mitigation as the evidence |
Each answer follows one order: the direct answer in a sentence, the evidence behind it, then a stop. The investor decides whether to go deeper.
A London Business School summary of peer-reviewed research by Kanze and co-authors (Academy of Management Journal, 2018) reports that responding to prevention-focused questions with promotion-focused answers raised more funding in the study. A prevention-focused question asks what could go wrong; a promotion-focused answer names the risk in a sentence and moves to what the company gains by getting past it.
If you can't source a number in the room, name the day you'll send it, and send it that day.
How to protect an idea before showing it to investors
To protect an idea before it's shown, a company controls three things: what it files, what it keeps secret and the order in which it shows things. The USPTO's patent basics say an idea or suggestion alone can't be patented; a filing has to describe an invention.
The first instinct is to ask investors for an NDA. Cooley's guide on requiring an NDA for investors says professional investors nearly always refuse to sign NDAs before a pitch, and its example of when an NDA can make sense is specific IP at the core of the company's value that isn't yet the subject of filed patents.
A trade secret keeps that status only while its owner has taken reasonable measures to keep it secret, so what's shown, to whom and when is part of the protection.
Staged disclosure follows from that: show the claim and the result, and keep the method back. Where the core of the value is a technology no filing covers yet, counsel can file a provisional application before the method is shown, and the data room opens only to a named counterparty.
How to present a pitch deck in three disclosure stages
4 columns. Drag the table sideways; the first column stays put.
Stage | Shows | Protection in place | Who signs |
|---|---|---|---|
Teaser | The claim and the evidence | Nothing in it lets a reader rebuild the method | Nobody |
Presentation | The result: product, traction, numbers | Filings made for any core technology; trade secret measures | Usually no NDA |
Data room | The method, contracts and detail | Access limited to named counterparties | The investor signs an NDA before access |
| Item | Reveals how it is built (0 to 100) | Value to the investor's decision (0 to 100) | Note |
|---|---|---|---|
| The claim | 10 | 74 | What the company does and for whom. |
| The result | 32 | 92 | Product, traction and the numbers behind it. |
| The method | 84 | 66 | How it works; detail for the data room. |
| Raw data and code | 94 | 24 | Only after diligence starts. |
An NDA is signed before the data room opens, so the method reaches only investors who have signed one.
What the data room holds at the diligence stage is covered in investor due diligence. Counsel confirms the route for the company's jurisdiction; this section describes practice and isn't legal advice.
What happens after you leave the room?
Part of an investor's work on a deal happens after the meeting, in conversations the company isn't part of, and what the company sent decides what gets repeated in them.
Send the forwardable PDF version the same day, with every answer promised in the room put in writing.
Ask who else needs to see it, and offer to brief them.
Agree the next step with a date before the call or the meeting ends.
Name the stage after this one, whether diligence questions, a data room or term discussions, and prepare it before it's asked: the diligence question list, the data room index and the capitalization table.
If the investor goes quiet, send one follow-up that carries new information.
| Step | Leads to |
|---|---|
| Meeting ends | Same day: PDF and written answers |
| Same day: PDF and written answers | Investor replies? |
| Investor replies? | Next step agreed, with a date [yes]; One follow-up with new information [no] |
| Next step agreed, with a date | end |
| One follow-up with new information (a changed number, a new answer) | end |
When there is a mutual contact, a warm introduction to a second partner at the fund reaches the decision another way than a reminder to the first.
How do you judge whether your pitch deck presentation worked?
Whether the meeting worked shows in what the investor says and does next: they repeat your claim in their own words, ask who else needs to see the material, name a next step or bring in a colleague.
When none of that happens, ask which part of the argument didn't land, and fix that slide before the next meeting.
Add the investor's questions to your answer sheet with the date. A question that comes back from a second investor belongs in the deck itself.
How spectup prepares a pitch deck presentation
spectup works for the company that's presenting, and for no one else in the transaction. A deck runs 12 to 19 days from accepted proposal to delivery. On a full 19-day job roughly three days go to strategy, four to the story, five to research and seven to design, so the pacing for a fifteen-minute meeting is drawn last, after the argument is fixed.
Each number on a slide names its source, and the research drops anything it can't stand up twice. Where the two licensed market databases disagree, the deck carries the lower figure and names which one it came from.
The company receives the deck editable in PowerPoint, Google Slides, Keynote or Canva, a PDF for sending and the research appendix.
On a capital introduction mandate, every meeting is briefed to the client 48 hours before it happens when the client takes the investor calls. Where spectup runs the conversation, every objection an investor raises goes back into the materials.
How to present a pitch deck at your next meeting: what to settle first
If you want the deck built with spectup, the pitch deck service starts with a 30-minute call, then a proposal with scope, fixed fee and a 12 to 19 day timeline.
Write down which of the four is missing today (the opening claim and one ask, the answer sheet, the dated follow-up, the line between the slides and the data room), and fix that one first.
Three conclusions
Investors spend under 3 minutes reviewing a deck, so the first minute of the talk confirms what they read or corrects it, and everything after adds the reasoning the pages leave out.
An idea alone can't be patented, investors rarely sign an NDA before a pitch, and a trade secret survives only with reasonable measures. That leaves the filing, the secrecy measures and the order in which things are shown.
Send the forwardable PDF and the promised answers the same day, agree a dated next step, and write again only when there is something new to say.
Presenting a pitch deck: questions readers ask
7 questions on capital raising materials, answered by Niclas Schlopsna, Managing Partner.
01What is a pitch deck presentation?
A pitch deck presentation is the deck as it is spoken to investors in a meeting, with the speaker adding the argument to the evidence on the slides. The material usually exists in two versions: a teaser the investor reads alone and a presentation version the speaker uses.
02How long should a pitch be?
A first meeting gets a short talk with the investor's questions woven through it; spectup builds decks for a fifteen-minute meeting. A partner or committee meeting runs longer because the questions go deeper. A follow-up after diligence questions is a written answer pack with no talk at all.
03What should you not say to investors?
Any number you can't source, any claim about a competitor you can't support, and anything the data room will contradict later. When you don't have an answer in the room, say so and name the day you'll send it.
04Should I require investors to sign an NDA before reviewing my pitch deck?
Usually not. Professional investors nearly always refuse to sign an NDA before a pitch, and Cooley's guide for companies gives one example of an exception: specific IP at the core of the company's value that isn't yet the subject of filed patents. In that case counsel files first or sets terms before the method is shown. Otherwise the NDA belongs to the data room, once a named counterparty asks for the detail.
05How do you pitch an idea without it being stolen?
Show the claim and the result first and keep the method for the data room, behind an NDA. Check with counsel before any disclosure whether the core technology needs a filing. A trade secret stays one only if its owner takes reasonable measures to keep it secret, so what you show, to whom and when is part of the protection.
06Can I patent a business idea?
Not as an idea alone. The USPTO says an idea or suggestion by itself can't be patented, and a filing has to describe an invention. Whether a specific technology qualifies is a question for a patent attorney, ahead of the first pitch.
07Should a company hire a pitch deck service before its investor meetings?
Yes, when the argument isn't settled yet or the same material has to work as a teaser and as a presentation. A pitch deck service fixes the positioning, equity story and market research first, then designs the pages for a short meeting and for the forwarded PDF. A company that already knows how to make a good pitch deck, with a settled argument and its own designer, can brief both versions itself.